
[ad_1]
AlphaStreet Newsdesk powered by AlphaStreet Intelligence
 SO|EPS $1.32 vs $1.25 est (+5.6%)|Rev $8.40B|Net Income $1.36B
Stock $95.10 (+1.7%)
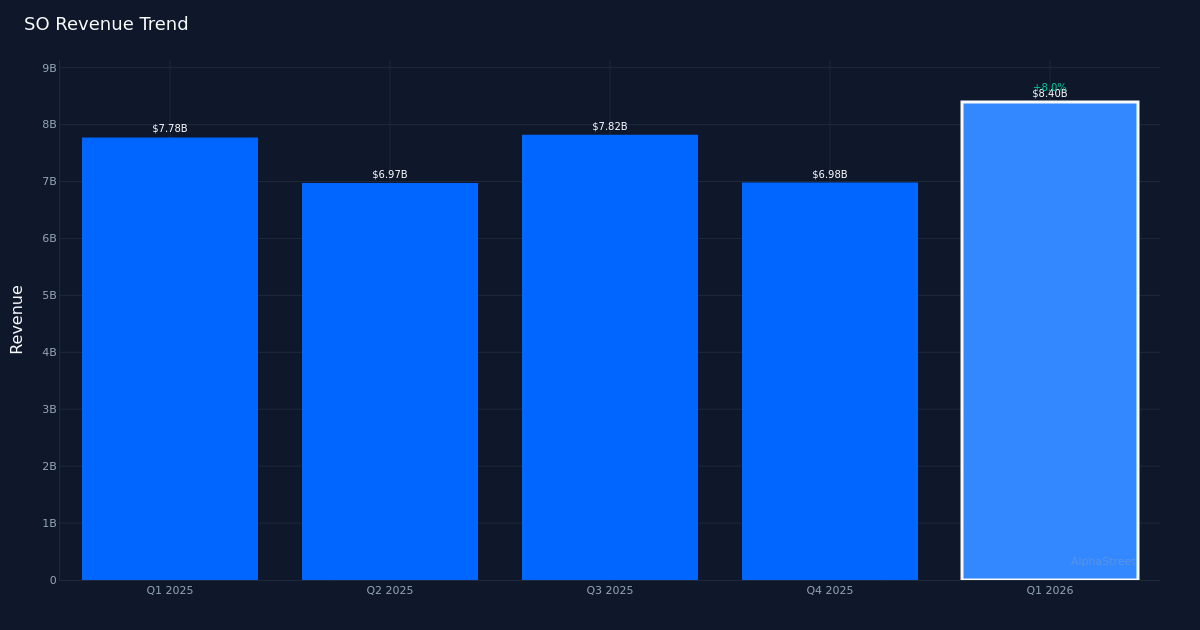
Solid earnings beat. The Southern Company (NYSE: SO) posted Q1 2026 adjusted EPS of $1.32, topping the Street’s $1.25 estimate by 5.6%, as the regulated utility operator delivered revenue growth across its operating footprint. Revenue totaled $8.40B for the quarter, up 8.0% from $7.78B in Q1 2025, while net income reached $1.36B. Shares traded up 1.7% to $95.10 following the print, reflecting investor confidence in the company’s ability to drive top-line expansion in a capital-intensive sector.
Revenue-led performance. The quality of this beat appears robust, driven primarily by strong revenue growth rather than aggressive cost management alone. The 8.0% year-over-year revenue increase demonstrates the company’s pricing power and customer base expansion, with the company serving around 9 million regulated utility customers at quarter-end. This top-line momentum suggests Southern Company is capturing both volumetric growth and favorable rate dynamics across its regulated territories, a more sustainable earnings driver than one-time expense reductions in the utility sector.
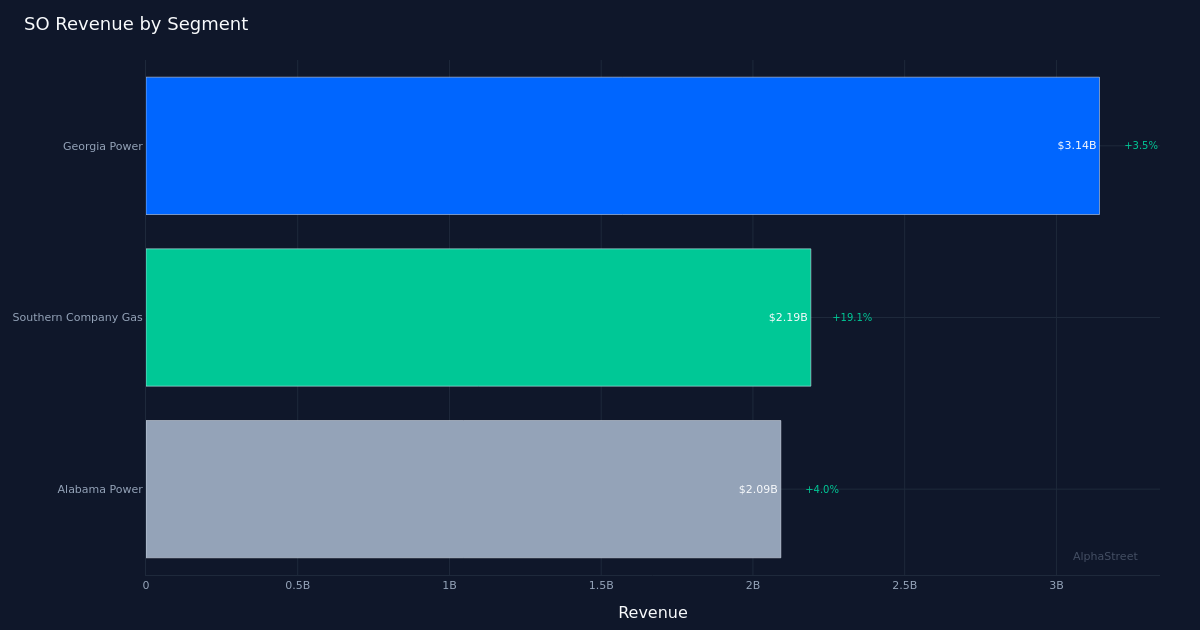
Gas segment shines. Southern Company Gas emerged as the standout performer, generating $2.19B in revenue with impressive 19.1% year-over-year growth. This segment’s acceleration significantly outpaced the company’s overall revenue growth rate, indicating strong natural gas distribution demand and potentially favorable regulatory outcomes on rate cases. The gas division’s performance becomes particularly noteworthy as utilities navigate the energy transition, with natural gas serving as a critical bridge fuel for reliability and baseload power generation.
Regulated model advantages. Operating within a regulated utility framework provides Southern Company with relative earnings visibility compared to merchant power generators, as cost recovery mechanisms and authorized returns on invested capital offer downside protection. The company’s ability to beat estimates while growing its customer base underscores the stability of its rate-regulated business model. This structure typically allows utilities to pass through prudently incurred costs to ratepayers while earning predetermined returns on infrastructure investments.
Mixed Street sentiment. Analyst opinion remains divided on the stock, with Wall Street consensus standing at 9 buy ratings, 17 hold ratings, and just 1 sell. This cautious positioning likely reflects the typical valuation premium utilities command during earnings growth phases, balanced against interest rate sensitivity that pressures regulated utilities’ discounted cash flow valuations. The modest positive stock reaction suggests the market is rewarding execution but remains mindful of sector-wide headwinds.
What to Watch: Southern Company’s ability to sustain double-digit growth in its gas segment while managing regulatory relationships across multiple jurisdictions will determine whether this quarter represents a new earnings trajectory or a seasonal anomaly. The trajectory of customer additions and any commentary on capital expenditure plans for grid modernization and renewable integration will signal long-term earnings power beyond 2026.
This content is for informational purposes only and should not be considered investment advice. AlphaStreet Intelligence analyzes financial data using AI to deliver fast and accurate market information. Human editors verify content.
[ad_2]
Source link