
[ad_1]
AlphaStreet Newsdesk powered by AlphaStreet Intelligence
 LH|EPS $4.25 vs $4.22 est (+0.7%)|Rev $3.54B|Net Income $277.8M
FY26 EPS guidance – adjusted $17.70 – $18.35|Stock $257.14 (-0.9%)
EPS YoY +10.7%|Rev YoY +5.8%|
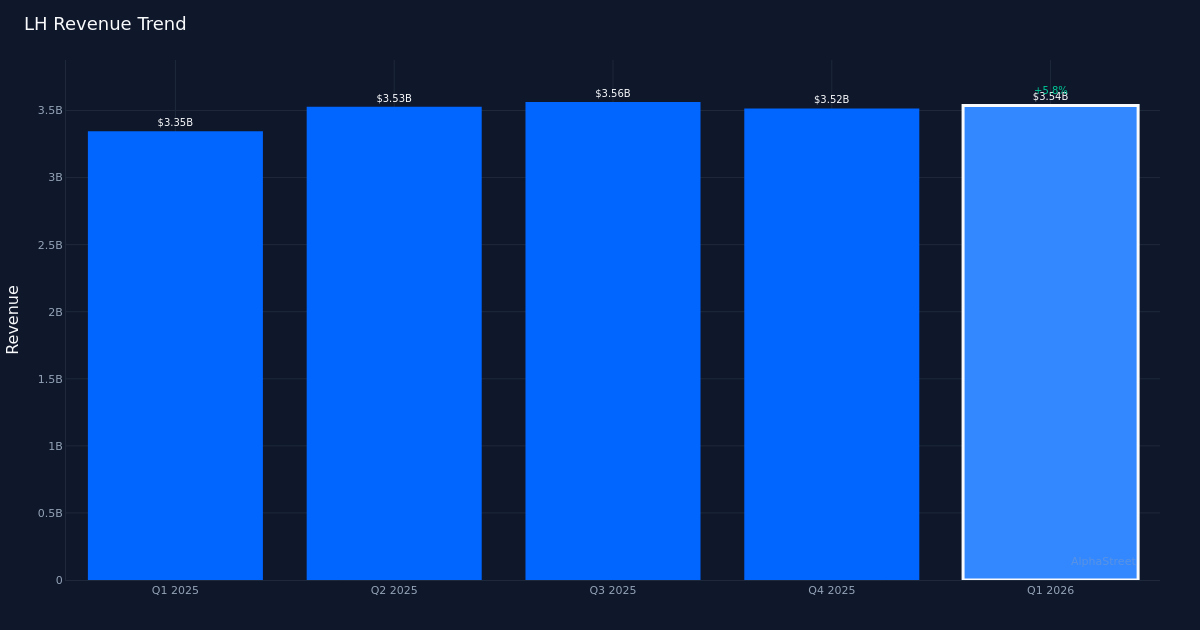
Labcorp (LH) delivered a modest but clean beat in Q1 2026, combining top-line momentum with meaningful margin expansion. The diagnostics and research services provider posted adjusted EPS of $4.25, edging past the $4.22 consensus by 0.7%, while revenue of $3.54 billion represented 5.8% year-over-year growth. More importantly, the company demonstrated earnings quality through simultaneous revenue growth and margin improvement.
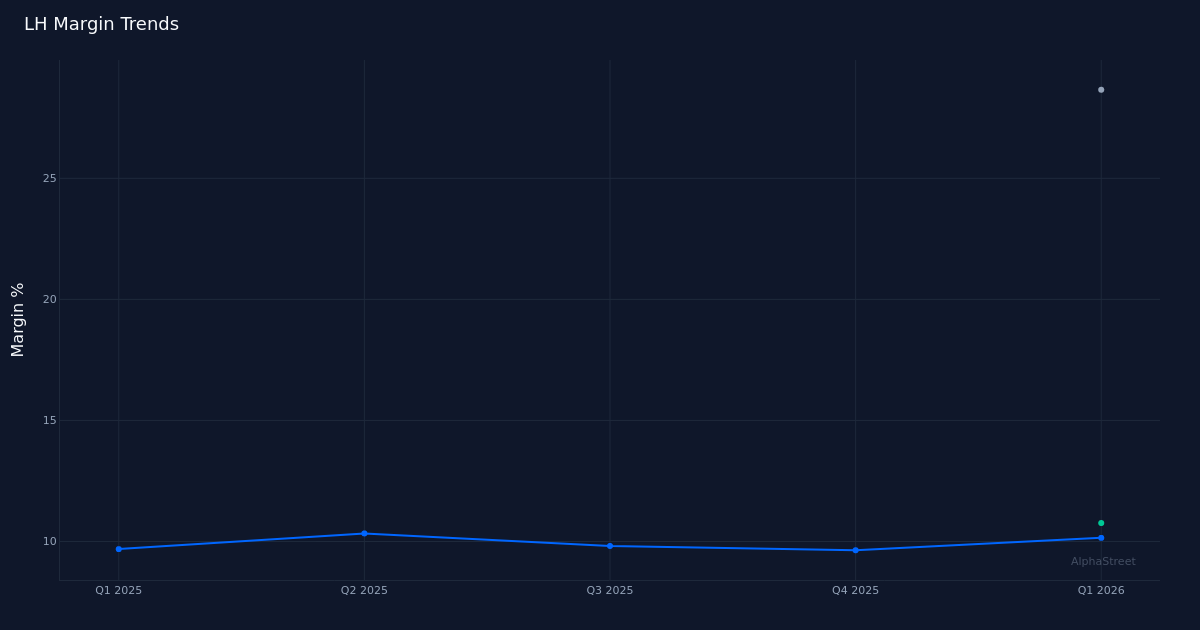
The margin story reveals genuine operating leverage rather than financial engineering. Net margin improved year-over-year, while operating margin reached 10.8%. Management noted that “enterprise adjusted operating margin, expanding more than 30 basis points to 14.4%,” indicating the company is extracting real efficiency gains as revenue scales. This stands in contrast to cost-cutting masquerading as performance improvement. The 10.7% year-over-year EPS growth notably outpaced the 5.7% revenue growth, underscoring the operating leverage thesis.
Revenue trajectory shows stabilization after recent volatility, though sequential momentum remains muted. The four-quarter trend reveals revenue oscillating in a tight $3.52 billion to $3.56 billion band, with Q1 2026’s $3.54 billion landing near the middle of that range. This quarter’s 5.8% year-over-year growth represents a slight acceleration from the 5.7% reported in the year-ago comparison, but the sequential pattern suggests Labcorp is operating in a relatively steady-state demand environment. Management acknowledged external headwinds, noting “if you look at weather in the first quarter, we estimate it was about a $15 million impact for the quarter,” which implies underlying performance may have been marginally stronger absent these temporary factors.
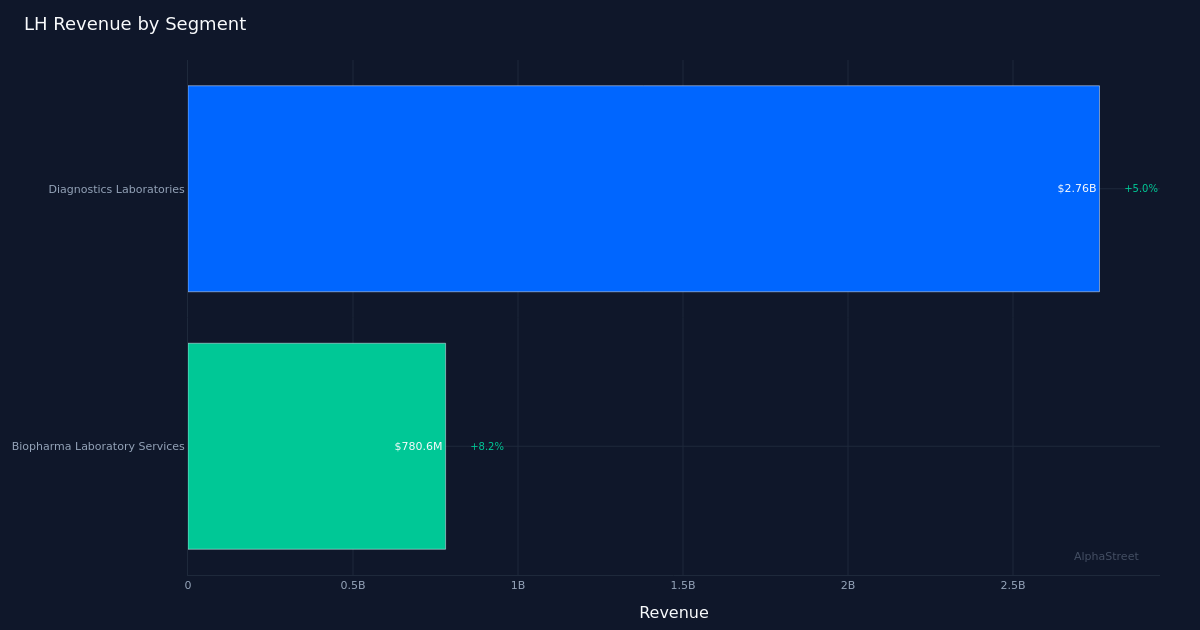
Segment performance reveals divergent trajectories with Biopharma Laboratory Services driving outperformance. The smaller Biopharma segment generated $780.6 million in revenue with 8.2% growth, materially outpacing the core Diagnostics Laboratories segment’s 5.0% growth on a much larger $2.76 billion base. This bifurcation matters because it signals where Labcorp’s growth engine sits. The Biopharma segment’s faster expansion likely reflects ongoing strength in drug development activity and clinical trial demand, while the Diagnostics business appears more tethered to routine healthcare utilization trends. Management characterized diagnostics performance positively, stating “if you look at diagnostics revenue, we had a 5% increase over last year, reached $2.8 billion if you look at the organic growth, it was about 3%,” though the distinction between reported and organic growth suggests acquisition contributions are providing a meaningful boost to headline figures.
Guidance suggests management sees a continuation of current trends rather than inflection. The full-year 2026 adjusted EPS guidance of $17.70 to $18.35, with an $18.02 midpoint, implies relatively balanced performance across the remaining three quarters. Given Q1’s $4.25 result, the guidance midpoint of $18.02 suggests approximately $13.77 in EPS across the final three quarters, or roughly $4.59 per quarter. This would represent modest sequential acceleration from Q1, consistent with typical seasonality patterns in laboratory services. Revenue guidance of $14.61 billion to $14.80 billion indicates expected full-year growth in the mid-single digits, aligning with Q1’s performance. The 5.6% backlog growth provides some forward visibility and suggests the revenue guidance carries a reasonable probability of achievement.
The muted stock reaction suggests the market had largely priced in this performance level. Shares trading largely unchanged following the release indicates neither meaningful positive nor negative surprise relative to investor expectations. With a beat rate of 100% over the most recent quarter tracked, Labcorp has established a pattern of meeting or exceeding expectations, which may have reduced the threshold for generating positive stock momentum from a modest 0.7% earnings beat.
Workforce stability at 71,000 employees provides context for the margin expansion story. The company’s ability to grow revenue 5.8% while presumably maintaining relatively stable headcount suggests productivity improvements are contributing to margin gains, though without prior-period employee counts this remains qualitative observation rather than quantitative confirmation.
What to Watch: The sustainability of Biopharma segment outperformance will determine whether Labcorp can maintain or accelerate its growth trajectory, particularly as clinical trial activity remains sensitive to biotech funding conditions. The conversion of the growing backlog into revenue provides a near-term leading indicator for Q2 performance. Finally, management’s ability to deliver on the upper half of guidance would require sequential acceleration in the back half of 2026, making Q2 results critical for validating the full-year outlook.
This content is for informational purposes only and should not be considered investment advice. AlphaStreet Intelligence analyzes financial data using AI to deliver fast and accurate market information. Human editors verify content.
[ad_2]
Source link